US Energy Storage Surpasses 200 GWh, Adding 14.3 GWh in the Third Quarter
Key Takeaways
- OpenRouter Removes Three AI Inference Providers After Prompt TheftIT & Security Director
- How to verify supplier credentials in global chemical sourcingLead Materials Scientist
- National Cybersecurity Standards Committee Seeks Feedback on Three GuidelinesIT & Security Director
- How to verify specialty chemical exporters in IndiaLead Materials Scientist
- Trump Fires National Cyber Director, Names Kirsten Davies Acting DirectorIT & Security Director
- Can mobile POS systems accept payments without internet access?IT & Security Director
- Malaysia and US Deepen Sovereign AI Cloud Cooperation, With $50 Million in US SupportIT & Security Director
- How chemical recycling is reshaping plastics technology in EuropeLead Materials Scientist
Industry Overview
We do not just publish news; we construct a high-fidelity digital footprint for our partners. By aligning with TNE, enterprises build the essential algorithmic "Trust Signals" required by modern search engines, ensuring they stand out to high-net-worth buyers in an increasingly crowded global digital landscape.
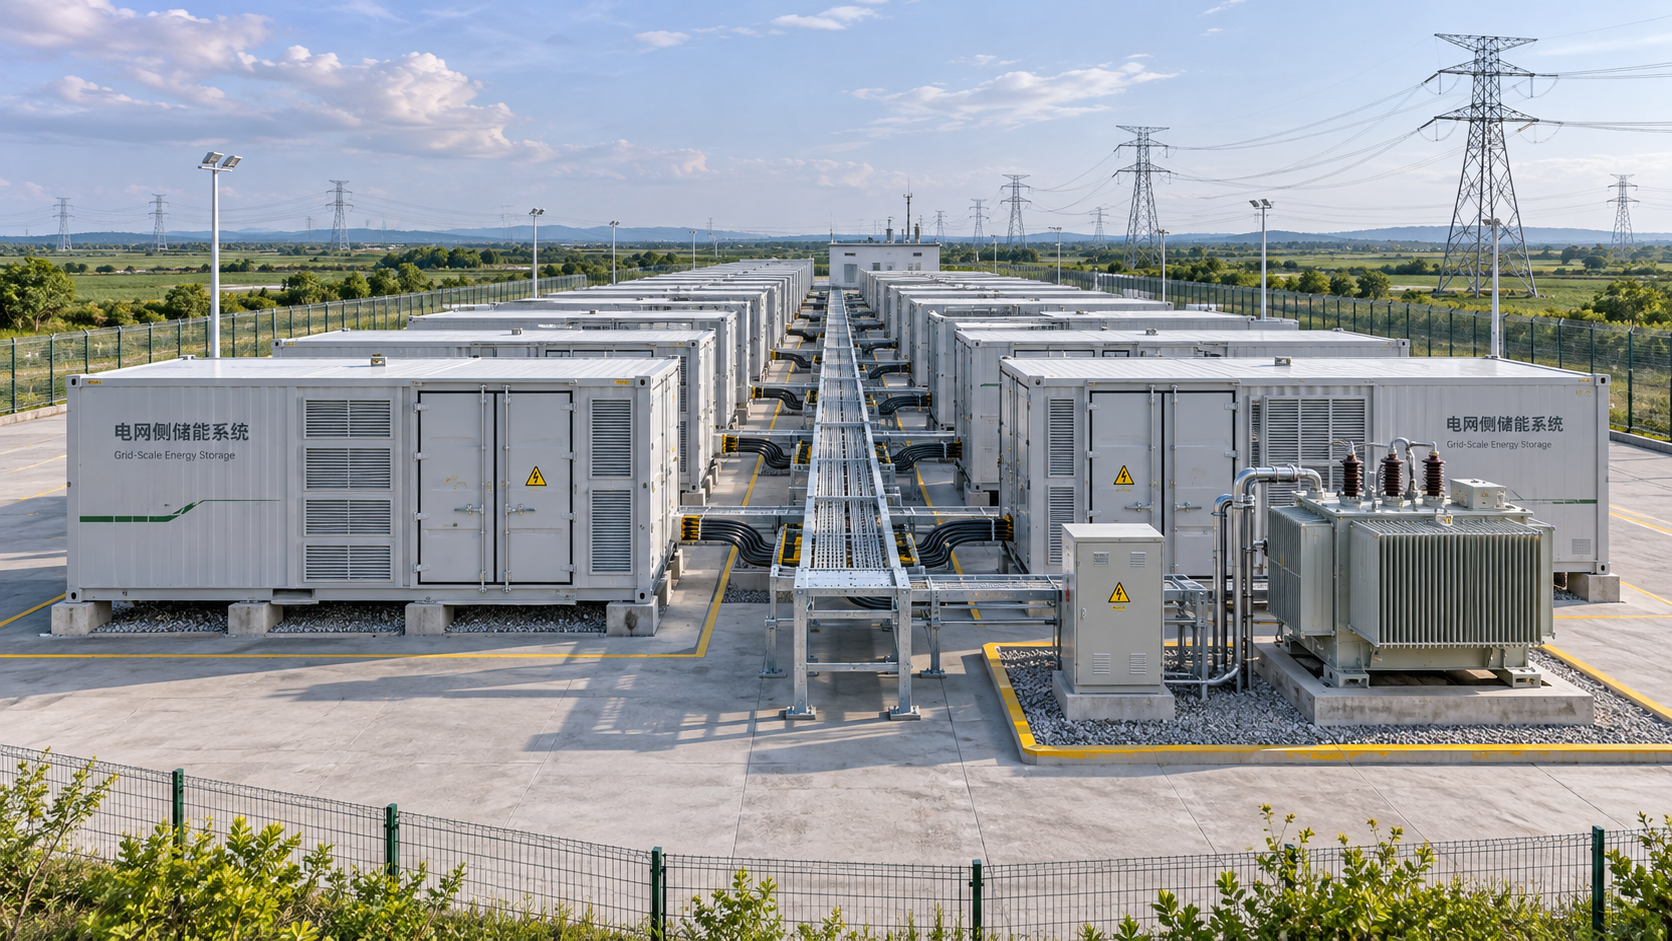
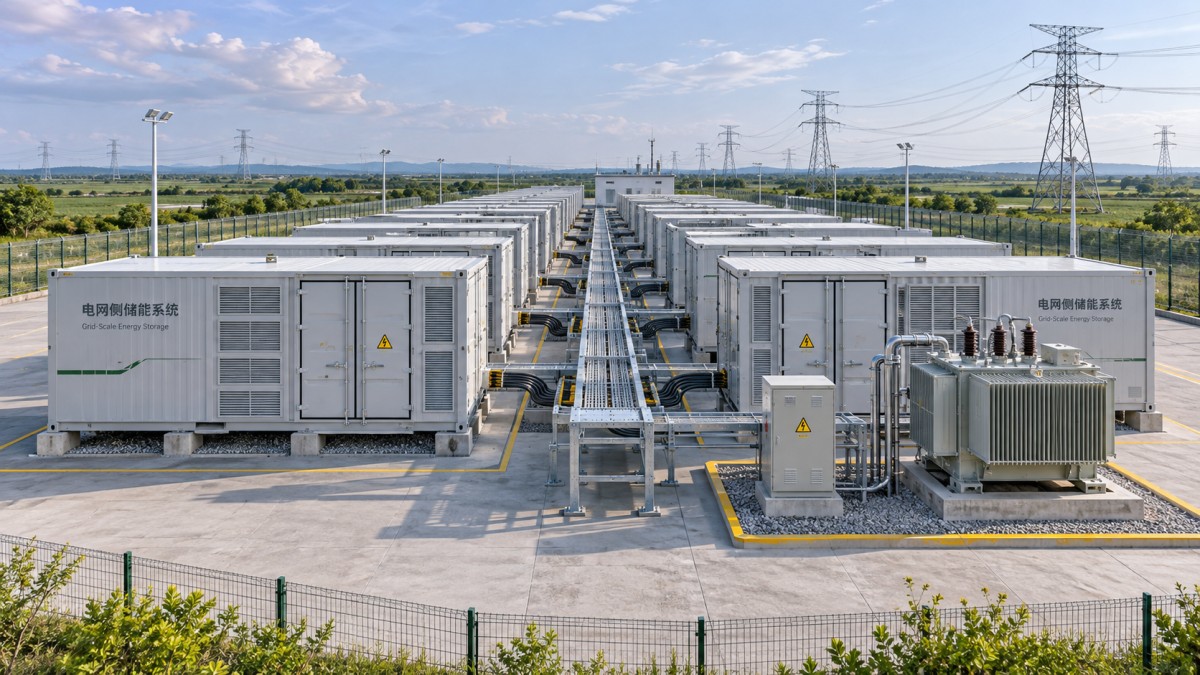
US energy storage installations reached a reported milestone in the third quarter of 2026, when additions of 14.3 gigawatt-hours pushed cumulative capacity above 200 GWh, according to a market outlook from the Solar Energy Industries Association (SEIA). The supplied report summary does not identify a new policy, regulation or technical standard. For utilities, energy buyers and storage suppliers, the immediate regulatory question is therefore how existing and future project requirements may apply as deployment expands, rather than whether a new nationwide rule has taken effect.
Quarterly additions take cumulative storage above 200 GWh
SEIA’s latest market outlook reports that the US energy storage industry added 14.3 GWh of installed capacity in the third quarter of 2026. Those additions brought cumulative installed energy storage capacity in the country above 200 GWh.
The supplied summary also states that grid operators, utilities and energy buyers are accelerating the deployment of storage systems to optimize electricity costs and support grid stability. It does not provide a breakdown of the additions by project, buyer or technology, or identify a policy or rule change associated with the reported milestone.
Storage procurement moves into closer focus
Buyers need capacity claims to match project needs
From an industry perspective, the reported increase in deployment may prompt buyers to examine more closely how proposed storage capacity relates to the operating outcomes they seek. A procurement document can distinguish the energy a system is intended to store from the conditions under which the buyer expects it to operate. The reported GWh figures describe energy capacity; on their own, they do not establish the power output, operating duration or performance of an individual project.
Utilities and other energy buyers may therefore find it useful to review technical proposals alongside project-specific operating assumptions. Where a tender refers to cost optimization or grid stability, bidders could be asked to explain how their proposed system supports those objectives and how performance will be assessed. This is a procurement consideration, not a new requirement established by the SEIA summary.
Suppliers and integrators may face closer document review
For equipment suppliers and system integrators, analysis suggests that a larger volume of storage projects could increase the importance of consistent technical documentation. Product descriptions, proposed operating conditions, test evidence and delivery commitments may all inform whether a bid meets a particular buyer’s specifications. The input does not establish that any of these documents have recently changed or that a particular certification is now mandatory.
Suppliers may benefit from identifying which evidence a customer requests at the bidding stage and which evidence must be available before delivery or acceptance. Integrators may also need to reconcile documentation from different equipment suppliers so that the proposed system can be evaluated as a whole. The practical requirements will depend on the project and the applicable documents, rather than on the cumulative installation figure itself.
Contractors and service providers must account for the full delivery process
Project contractors and service providers may encounter a wider range of questions about delivery, installation, commissioning and ongoing support as buyers plan storage deployments. A system that meets a proposed capacity specification still has to be delivered and assessed under the terms agreed for the project. For that reason, analysis suggests that the division of responsibilities among the buyer, contractor, equipment supplier and service provider deserves attention early in procurement.
Those responsibilities could include providing technical records, explaining test results, resolving discrepancies and maintaining traceability for supplied equipment. The supplied information does not identify delays, service failures or changes to delivery rules. These are potential areas for review, not reported problems in the third quarter.
Trade and supply arrangements remain project dependent
For businesses supplying equipment across borders, the reported US deployment level may be relevant to commercial planning, but it does not establish a change in tariffs, customs procedures or market access. Companies considering a shipment could check the trade requirements and documentation applicable to the goods and transaction in question, as well as any customer conditions that affect acceptance.
Similarly, procurement teams may wish to assess whether proposed suppliers can provide the required documentation and meet agreed delivery dates. The event summary does not identify a shortage, a change in sourcing rules or a particular country of origin. Any assessment of those matters would require evidence beyond the supplied information.
What to verify before a storage contract is signed
Translate project objectives into measurable terms
Because the stated reasons for deployment include electricity cost optimization and grid stability, buyers and bidders could first establish how those objectives are reflected in a specific project. Relevant questions may include what capacity is being purchased, which operating conditions the proposal assumes and how performance will be demonstrated at acceptance. Clear descriptions may help the parties identify differences between a headline capacity figure and the obligations in a contract.
These checks are particularly useful when comparing bids that describe system capabilities in different ways. They should be treated as suggested due diligence: the input does not specify a mandatory procurement method or a uniform performance test.
Check certification and testing against the actual tender
Before relying on a certificate, test report or technical statement, a buyer or supplier could verify its scope and whether it corresponds to the equipment and configuration proposed for the project. Where a tender or applicable authority specifies particular evidence, the parties should examine the relevant wording directly. If the position is unclear, seeking clarification during procurement may reduce the risk of disagreement later in delivery.
No certification scheme, standard number or revised testing rule is identified in the supplied summary. Companies should therefore avoid treating the reported installation milestone as proof that a particular certification has become mandatory or that an existing approval is sufficient for every project.
Align delivery records and responsibilities
Analysis suggests that contracts may be easier to administer when the parties identify the documents expected at each stage, the party responsible for producing them and the process for resolving omissions. Depending on the transaction, those records could include equipment specifications, supplier declarations, test documentation and acceptance records.
Buyers may also wish to compare promised delivery dates with project schedules and clarify how substitutions would be reviewed. A proposed alternative component or product could require technical assessment against the agreed specification before it is accepted. The summary does not say that substitution rules have changed; the point is to establish a project-specific process before a substitution becomes necessary.
Monitor authoritative updates and purchasing documents
Companies following the US storage market could review subsequent official statements, applicable regulatory information and the wording of relevant tenders for changes that affect their own transactions. Association publications may help track reported deployment, while the applicable authority or project documentation would need to be consulted to determine whether a binding requirement has changed.
This distinction matters for procurement and compliance teams. A market outlook can inform commercial expectations, but the supplied description of this one does not identify a new legal obligation, an implementation date or an enforcement approach. Internal decisions about certification, trade documentation or delivery should therefore be tied to verified requirements for the relevant activity.
A deployment signal, with rule changes still to be established
The reported milestone is best understood as a market deployment signal. It indicates, on the information supplied, that installed storage capacity has passed a stated level and that key buyers are accelerating deployment for cost and grid-related purposes. It does not by itself demonstrate that a new policy has been adopted or that a standard, certification process or trade rule has been revised.
Further observation would be needed to determine whether procurement practices or regulatory expectations change alongside deployment. Useful evidence could include official policy details, clarification from relevant authorities, revised tender language and feedback from companies implementing projects. A change in any one project’s specifications would also need to be assessed on its own terms before drawing conclusions about broader market practice.
There is a distinction between an individual buyer asking for more supporting evidence and a regulator imposing a new obligation. Both may matter to a supplier preparing a bid, but they have different sources and may apply to different sets of transactions. Keeping that distinction visible can help businesses respond to the documents that actually govern their work.
How businesses can use the milestone
For storage buyers and suppliers, the reported increase provides a reason to review project readiness: the clarity of capacity specifications, the completeness of supporting records, the allocation of delivery responsibilities and the availability of after-sales support. These are practical areas to examine as projects are planned or negotiated, rather than changes confirmed by the reported figures.
The balanced response is to use the SEIA-reported deployment data as context for commercial and procurement planning, while verifying any claimed compliance or trade change separately. The market figure alone cannot establish what a particular project must purchase, certify or deliver.
Basis for this report and points for verification
This article is based on the user-provided news title, event date and event summary, which attribute the installation figures to SEIA’s latest market outlook. A specific official source link was not provided in the input, and the underlying report and its figures remain to be verified. The article’s discussion of possible business effects and suggested checks is analysis, not additional information attributed to SEIA.
Follow-up verification could draw on the relevant association publication, official announcements, regulatory releases, standards organization documents and applicable tender materials. Policy details, certification interpretations, trade execution, industry feedback and company implementation should remain under observation where they are relevant to a particular transaction or project.
Deep Dive
Related Intelligence
 Battery TechLithium battery packs for off-grid telecom — why cycle life drops 40% below 15°CAnalyst:Automotive Tech Analyst
 Battery TechEVE Power Officially Becomes Tesla's Fifth Global Battery SupplierAnalyst:Automotive Tech Analyst
 Battery TechLithium battery packs in off-grid HVAC: Are thermal runaway risks being underestimated?Analyst:Automotive Tech Analyst