How Does Technology Forecasting Improve Raw Material Purchasing Cycles?
Key Takeaways
- How much RAM does edge computing hardware for IoT applications need?IT & Security Director
- How to evaluate precision livestock farming companies for grazing herdsAgri-Tech Strategist
- How to assess an agricultural machinery manufacturer's parts supportAgri-Tech Strategist
- What drives industrial automation cost in a new production line?Chief Civil Engineer
- What makes Ethiopia poultry farming profitable for small-scale producers?Agri-Tech Strategist
- How Does Technology Forecasting Improve Raw Material Purchasing Cycles?Lead Materials Scientist
- What Are the Biggest Risks of Single-Source Chemical Procurement?Lead Materials Scientist
- Are Cloud Procurement Platforms Worth It for Chemical Sourcing?IT & Security Director
Industry Overview
We do not just publish news; we construct a high-fidelity digital footprint for our partners. By aligning with TNE, enterprises build the essential algorithmic "Trust Signals" required by modern search engines, ensuring they stand out to high-net-worth buyers in an increasingly crowded global digital landscape.
How Does Technology Forecasting Improve Raw Material Purchasing Cycles?
How does technology forecasting help plan raw material purchasing cycles? It helps procurement teams see beyond today’s quote sheet. By bringing together production demand, material price signals, supplier capacity, logistics conditions, product design changes, and emerging process technologies, forecasting gives buyers a more realistic view of what they may need, when they may need it, and where their exposure sits.
That distinction matters because raw-material purchasing is rarely a simple exercise in finding the lowest available price. A resin buyer may be managing grade approvals and color consistency. A construction materials manufacturer may need to account for regional project schedules and transport constraints. A battery-component purchaser may be watching technology shifts that alter chemistry requirements before the next sourcing contract expires. In each case, buying too late can be expensive—but buying too early, or locking into the wrong specification, can be just as damaging.
Technology forecasting does not eliminate uncertainty. It gives teams a disciplined way to work with uncertainty before it becomes an urgent shortage, a production interruption, or a margin problem.
Purchasing Cycles Fail When They Are Based Only on Historical Consumption
Many purchasing cycles still begin with a familiar formula: last year’s consumption, adjusted by a sales forecast, plus a safety-stock allowance. That approach can work for stable, mature products with consistent demand and well-established suppliers. It becomes unreliable when the market is changing faster than internal planning assumptions.
Consider a manufacturer introducing a lightweight component, a lower-carbon formulation, or a product designed around new regulatory expectations. Historical material usage may no longer describe future requirements. A shift from conventional plastic to a biodegradable polymer, for example, can affect not only material cost but also moisture handling, processing windows, approved supplier options, shelf-life considerations, and the lead time required for qualification. The procurement plan has to reflect those realities well before the material appears on a purchase requisition.
The same issue appears in food systems, smart construction, auto and e-mobility, and enterprise technology supply chains. Demand is not driven solely by customer orders. It is also shaped by design roadmaps, capacity additions, product launches, regional policy changes, supplier investment decisions, and technical substitution. Forecasting makes these signals visible earlier.
Technology Forecasting Connects What Procurement Often Sees Separately
The practical value of forecasting lies in connecting datasets that are usually held by different functions. Procurement may know current lead times and supplier terms. Engineering may know which material grades are being tested. Operations may know where line capacity is tight. Sales may see demand changes first, while finance is focused on working capital. If those signals remain disconnected, purchasing becomes reactive by default.
A useful forecasting process does not require a perfect prediction model. It requires a shared view of the variables that can materially change a buying decision. The most relevant inputs usually include:
- expected production volumes by product family, plant, and region;
- engineering changes that may alter a material grade, formulation, or bill of materials;
- supplier capacity expansions, shutdowns, geographic concentration, and qualification status;
- price drivers such as feedstock exposure, energy intensity, currency risk, and freight conditions;
- inventory aging, storage limits, minimum order quantities, and warehouse constraints;
- technology developments that could increase demand for a material or make an existing grade less suitable.
This is where technology intelligence changes the quality of the purchasing discussion. Instead of asking, “Should we buy more this quarter?” the team can ask better questions: “Will this grade still be approved after the next product revision?” “Are more manufacturers likely to compete for this input?” “Can a supplier’s announced capacity increase actually serve our required geography and specification?” “What is our fallback if a material becomes technically obsolete rather than merely more expensive?”
Those are strategic questions, but they have very operational consequences: contract duration, order timing, inventory policy, supplier development, and qualification priorities.
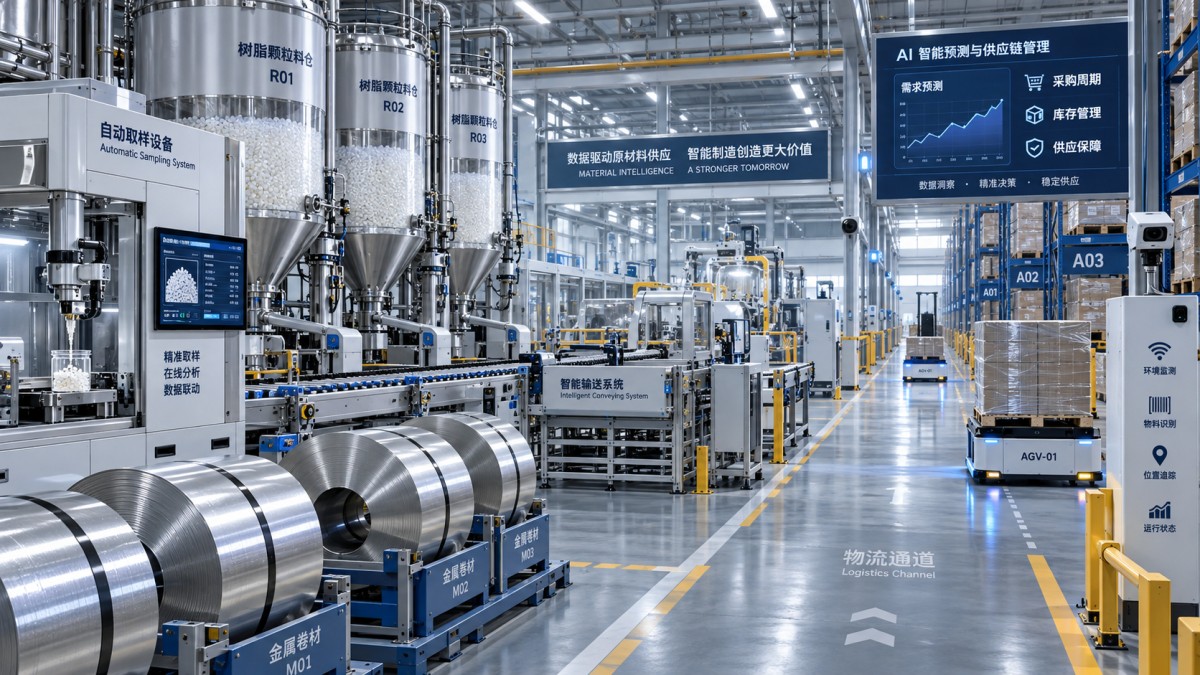
Earlier Demand Signals Improve Timing, Not Just Forecast Accuracy
Purchasing teams often focus on forecast accuracy as though it were the only measure that matters. In practice, timing is often more valuable. A forecast that identifies a likely material constraint six months early can be more useful than a highly precise forecast delivered after suppliers have allocated capacity elsewhere.
Technology forecasting helps create that earlier window. For instance, if product development teams are moving toward higher-performance coatings, advanced composites, alternative battery materials, or specialized electronic components, procurement should not wait until final commercial volumes are confirmed. It should map potential material demand, understand qualification lead times, and identify where the supply base is narrow. Early engagement does not always mean placing a large order. It may mean securing samples, reserving technical support, negotiating an option mechanism, or beginning dual-source validation.
There is a common mistake here: treating all early indicators as commitments. They are not. A technology roadmap, a pilot program, or a public supplier announcement may change direction. The appropriate response is proportional. High-confidence signals may justify longer-term supply planning. Lower-confidence signals may only justify scenario analysis and supplier conversations. Good forecasting distinguishes between a probable demand shift and a confirmed purchasing obligation.
Price Forecasting Is Useful, but It Should Not Drive the Whole Decision
Raw material price intelligence is an essential part of purchasing-cycle planning, especially for inputs linked to energy markets, agricultural production, metals, petrochemicals, or constrained minerals. Yet buyers can get into trouble when they turn a price outlook into a single buying rule.
A projected price increase may support earlier purchasing, but only if the organization can store the material safely, preserve quality, finance the inventory, and use it before technical or commercial requirements change. Conversely, a predicted price decline may encourage delayed buying, but delay can be risky when supply continuity is already fragile. A lower market price does not help if a production line stops because a qualified grade is unavailable.
The better approach is to view price as one risk layer among several. A buyer should assess the landed-cost picture, not only the unit price: freight, duties where applicable, packaging, payment terms, handling losses, inventory carrying cost, and the cost of a potential quality failure all belong in the decision. For technically sensitive materials, the cost of requalification can outweigh a modest purchase-price difference.
Supplier Risk Becomes More Visible When Technology Is Part of the Forecast
A supplier can appear dependable on a scorecard and still become a future risk. This is especially true when its core technology, feedstock access, manufacturing location, or product portfolio is being disrupted. A supplier’s current on-time delivery performance cannot tell a buyer whether that supplier will continue investing in a declining material category, prioritize another market segment, or maintain technical support for a low-volume specialized grade.
Technology forecasting adds context to supplier risk management. It encourages buyers to examine whether suppliers are expanding the relevant production technology, whether competitors are building demand for the same inputs, and whether substitution is becoming commercially realistic. In some categories, the better decision is not to force a second source immediately. It may be more sensible to strengthen the existing relationship while funding internal trials for a credible alternative. The right answer depends on material criticality, switching costs, customer specifications, and the time required to validate a replacement.
This is why generic supplier diversification targets can be misleading. Two suppliers are not necessarily two viable sources if both rely on the same upstream feedstock, the same transport corridor, or the same proprietary processing route.
What a Better Raw Material Buying Cycle Looks Like
A mature cycle is not one giant annual forecast followed by monthly corrections. It is a rolling process with different decision horizons. Near-term planning addresses production continuity and confirmed orders. The medium horizon covers contract exposure, capacity planning, and supplier allocations. The longer horizon follows material innovation, product roadmaps, new regulations that may affect material choice, and structural shifts in the supply base.
The key is to assign an owner to each signal. Engineering should validate technical relevance. Procurement should assess market and supplier implications. Operations should define consumption and inventory constraints. Finance should challenge working-capital assumptions. Without ownership, forecasting often becomes an interesting slide deck rather than an input to actual buying decisions.
For cross-industry teams, the intelligence challenge is substantial. Advanced materials, agri-tech inputs, smart construction systems, e-mobility supply chains, and enterprise infrastructure each move at different speeds and use different technical language. Platforms such as TradeNexus Edge are useful when they help decision-makers connect technology developments with supply-chain realities rather than treating market news, engineering change, and procurement risk as separate topics. The value is in contextual interpretation: what a development may mean for sourcing, not simply that it happened.
FAQ: How Does Technology Forecasting Help Plan Raw Material Purchasing Cycles?
Does technology forecasting replace traditional demand planning?
No. Traditional demand planning remains the operational baseline for materials required to meet production schedules. Technology forecasting adds a forward-looking layer: it identifies changes that historical demand alone may miss, such as material substitution, emerging capacity constraints, process innovation, or a shift in end-market requirements. The two should inform each other.
Which raw materials benefit most from this approach?
The greatest benefit usually appears in materials with long lead times, few qualified suppliers, volatile cost drivers, complex technical specifications, or high requalification costs. Specialty chemicals, engineered polymers, battery-related materials, electronic inputs, coatings, composite materials, and certain agricultural inputs often fit this profile. Commodity categories can also benefit when logistics or regional availability is the main source of risk.
What is the biggest implementation mistake?
Treating a forecast as a certainty. Forecasting should guide choices under uncertainty, not create false confidence. Teams should use scenarios, define triggers for action, and revisit assumptions when new evidence appears. A purchasing plan that cannot be adjusted is usually more fragile than it looks.
How often should procurement teams update the forecast?
That depends on the material category and business rhythm. Fast-moving or highly exposed categories may need frequent review, while stable categories can be reviewed less often. The more important principle is event-based review: reassess the plan when a supplier announces a shutdown, engineering changes a specification, demand moves sharply, or a relevant technology development changes the supply outlook.
The strongest purchasing cycles are not built around guessing the exact future price of every material. They are built around knowing which assumptions matter, where lead times can become dangerous, and when a technical shift requires action before the market makes that action obvious.
Deep Dive
Related Intelligence
 Specialty ChemicalsSodium Methoxide Selection: How Chemical Buyers Reduce Specification and Handling RiskAnalyst:Lead Materials Scientist
 Specialty ChemicalsHow Corporate Case Studies Reveal Real-World Challenges in Adopting Specialty Chemicals for Food SafetyAnalyst:Lead Materials Scientist
 Specialty ChemicalsCan Brand Elevation Tactics Reduce Customer Acquisition Cost for Specialty Chemicals in Organic Food Production?Analyst:Lead Materials Scientist